GST refunds made easier; arrest powers cut
ECONOMY – POLICY
9 OCTOBER 2026
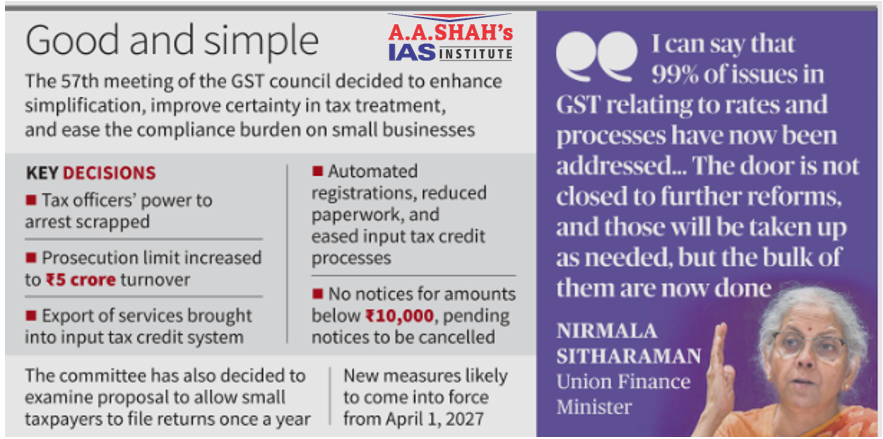
- The 57th GST Council meeting took place in New Delhi. It was held over a year after the previous meeting in September 2025.
- Core Objectives: Designed to enhance tax administration simplification, increase tax treatment certainty, clear input tax credit (ITC) processing bottlenecks, and lower compliance burdens—particularly for small businesses.
- Underlying Philosophy: Driven by the “principle of trust” toward taxpayers.
- Reforms Scope: According to Union Finance Minister Nirmala Sitharaman, 99% of GST rate and process issues have now been addressed. Future rate modifications will occur only once a year.
- Input Tax Credit (ITC): So far, taxpayers were denied input tax credits (ITC) until their suppliers had filed their returns. This meant that thousands of genuine businesses that had received supplies and paid taxes on them were denied ITC, leading to a drying up of crucial working capital. The GST Council has tasked a committee to find a solution that can be implemented by April 1.
- Effective Implementation Date: Changes are slated to take effect from April 1, 2027.
- The decision to review rates only once a year, and implement rate changes only at the start of financial years, removes significant uncertainty that usually arises each time the Council meets.
- In its 10th year, GST is finally starting to look like what it should have at the time of rollout.
Summary of Decisions & Reforms
| Domain | Key Action Taken | Directly Affected Parties / Business Impact |
| Enforcement Powers | Scrapped arrest powers of GST officers completely. | Prevents inspector intimidation and converts procedural defaults into civil matters. |
| Prosecution Threshold | Increased threshold from ₹1 crore to ₹5 crore. | Small to medium taxpayers facing minor discrepancies are exempt from criminal proceedings. |
| General Penalties | Reduced maximum general penalty from ₹25,000 to ₹10,000. | Lower financial liability for non-fraudulent administrative/procedural lapses. |
| Transit & Inspections | Restricted interstate transit checks solely to origin or destination state officers. | Eliminates arbitrary transit stops by intermediate state enforcement units. |
| Transit Authorization | Required “specific intelligence” and approval from a Joint Commissioner-level officer. | Smooths nationwide movement of freight and logistics efficiency. |
| E-Commerce Compliance | E-commerce sellers can register via platform operator warehouses. | Eliminates the need for small digital sellers to maintain physical offices across multiple states. |
| Small Consumer Businesses | In-principle approval for an optional annual return filing / quarterly payment scheme (turnover up to ₹5 crore). | Eases paperwork for approximately 1.6 million small consumer-facing businesses. |
| Refund Processing | Reduced refund acknowledgment window from 15 days to 10 days. | Speeds up formal processing confirmation. |
| Automated Refunds | 90% of risk-assessed claims released within 3 working days. | Drastically improves working capital liquidity for exporters and taxpayers. |
| Faceless Assessment | Introduction of a CGST faceless assessment system (framework before Budget 2027, rollout in 2027–28). | Minimizes direct contact between tax officials and businesses. |
| Tax Rates | No GST rates were modified during this meeting. | Ensures price stability and financial predictability for businesses. |